

Gold sovereigns and collectable coins
See our current gold sovereigns and collectable gold coins, with fast insured UK delivery.
Shop gold coins →Table of Contents
- Capital Gains Tax on gold investment explained
- CGT exempt gold coins list and legal tender status
- VAT on gold bullion UK: what you pay and what you don't
- Inheritance Tax on gold jewellery and collectible coins
- Gold held in pensions: SIPP and SSAS tax treatment
- Record-keeping and HMRC reporting requirements
- Tax implications of gold investment for non-residents
- Frequently Asked Questions
Last Updated: September 28, 2026
Capital Gains Tax on gold investment explained
Capital Gains Tax (CGT) is the tax you pay on the profit when you sell a gold investment for more than you paid for it, and understanding the tax implications gold investment requires knowledge of exemptions, rates, and reporting rules. HMRC applies CGT to most gold bullion and bars, but there are important exemptions for certain types of gold coins that make them attractive to investors seeking tax-efficient holdings.
The gain is your sale price minus acquisition cost, taxed at 10% or 20% depending on your income tax band. For the current tax year, the annual CGT allowance is £3,000; you only pay tax on gains above this threshold.
You're taxed only when you sell, not annually on price increases, giving you flexibility in managing tax liability.
CGT exempt gold coins list and legal tender status
Coins must be legal tender in their country of issue and contain at least 900 parts per thousand fineness to qualify for CGT exemption.
Exempt coins include British sovereigns (both full and half), Britannia coins, and other gold coins issued by the Royal Mint. The Royal Mint's official guidance confirms that these coins are both VAT-free and CGT-exempt. Gold2u's 2017 Queen Elizabeth II Full Gold Sovereign is an example of an exempt coin, struck in 22 carat gold at 0.916 fineness and legal tender, it qualifies for full CGT relief. Similarly, historical pieces like the 1871 Queen Victoria Full Gold Sovereign remain exempt despite their age, provided they meet the fineness and legal tender criteria.


Taxable coins include commemorative coins, numismatic pieces with value beyond their metal content, and foreign gold coins that don't meet the legal tender and fineness requirements. A coin that's primarily collectible rather than bullion-grade typically falls into this category.
Legal tender status, official recognition by the issuing government, is what exempts coins from CGT, even though their market value far exceeds face value.
VAT on gold bullion UK: what you pay and what you don't
Investment-grade gold bullion and certain coins are VAT-exempt; the price you see is the price you pay.
Bullion bars and coins must be at least 900 parts per thousand fineness and traded as investment assets. Gold2u's 1 Gram Tayer Gold Bar and 1 Gram Gold Emirates Bar are VAT-exempt examples.

Where VAT becomes relevant is if you sell gold jewellery or collectible pieces. Antique jewellery and numismatic coins with value beyond their metal content may be subject to VAT on sale, depending on how they're classified. The HMRC notice on VAT exemptions for gold clarifies that investment gold has a specific exemption, but items valued primarily for craftsmanship or rarity sit outside this protection.
VAT exemption is automatic for bullion and exempt coins. If selling jewellery or rare coins, confirm VAT treatment with your dealer beforehand.
Inheritance Tax on gold jewellery and collectible coins
Gold bullion and investment coins are included in your estate at market value on death. At the current IHT threshold of £325,000, estates below this pass tax-free; above it, IHT is charged at 40%.
Antique gold jewellery and collectible coins may qualify for IHT relief as works of art or objects of cultural significance, but criteria are strict and HMRC must agree.
IHT treatment of historical coins like the 1871 Queen Victoria Sovereign depends on HMRC classification as numismatic collectibles (potentially eligible for relief) or bullion investments. Professional valuation and documentation strengthen relief claims.
For straightforward bullion holdings, plan IHT into your estate strategy. Gold's portability and value density mean it's easy to overlook in estate planning, but it counts toward your threshold just like property or cash.
Gold held in pensions: SIPP and SSAS tax treatment
Gold held in a Self-Invested Personal Pension (SIPP) or Small Self-Administered Scheme (SSAS) is not subject to CGT or income tax on gains; you pay tax only on withdrawals in retirement.
A SIPP allows individuals to hold bullion-grade bars or coins (not jewellery or numismatic pieces). Contributions are pre-tax, and growth is entirely tax-free.
A SSAS operates similarly for business owners and partners, deferring taxation significantly for long-term wealth building.
You cannot access gold until pension age (currently 55, rising to 57 by 2028) and must use an approved custodian, not store it at home. Custody adds a small annual fee but ensures compliance and insurance.
For investors with substantial gold holdings, exploring a SIPP or SSAS with a financial adviser can reveal significant tax savings compared to holding gold outside a pension.
Record-keeping and HMRC reporting requirements
HMRC expects detailed records for gold disposals. When you sell, report the transaction on Self-Assessment and calculate your gain. Keep purchase date, cost (including fees), sale date, sale price, quantity, and fineness.
What counts as adequate evidence
For CGT reporting, complete the capital gains section of your Self-Assessment return. If gains exceed £3,000 (2026/27), declare the excess. HMRC requires contemporaneous documentation proving acquisition cost and disposal proceeds.
Contemporaneous documentation, created at transaction time, is far more persuasive than reconstructed records. Keep dealer invoices, order confirmations, certificates of authenticity, assay reports, and delivery notes. For bars, weight and fineness must match purchase documentation.
2017 Queen Elizabeth II Full Gold →
For coins, keep evidence of legal tender status and fineness (Royal Mint certificates or dealer specs). For inherited gold, obtain professional valuation at death date, HMRC requires qualified dealer or independent valuer stating fineness, weight, and price per gram.
Record retention and HMRC enquiries
HMRC can enquire up to four years after filing deadline. Retain records for at least this period; six years is recommended for extended enquiry windows.
If HMRC enquires, they will request original purchase invoices, proof of payment, sale documentation, dealer correspondence, death certificates and valuations (for inherited gold), and scheme statements (for pensions). Failure to produce documents weakens your position; HMRC may estimate acquisition cost, resulting in higher tax. The burden of proof lies with you.
Structuring records by gold type
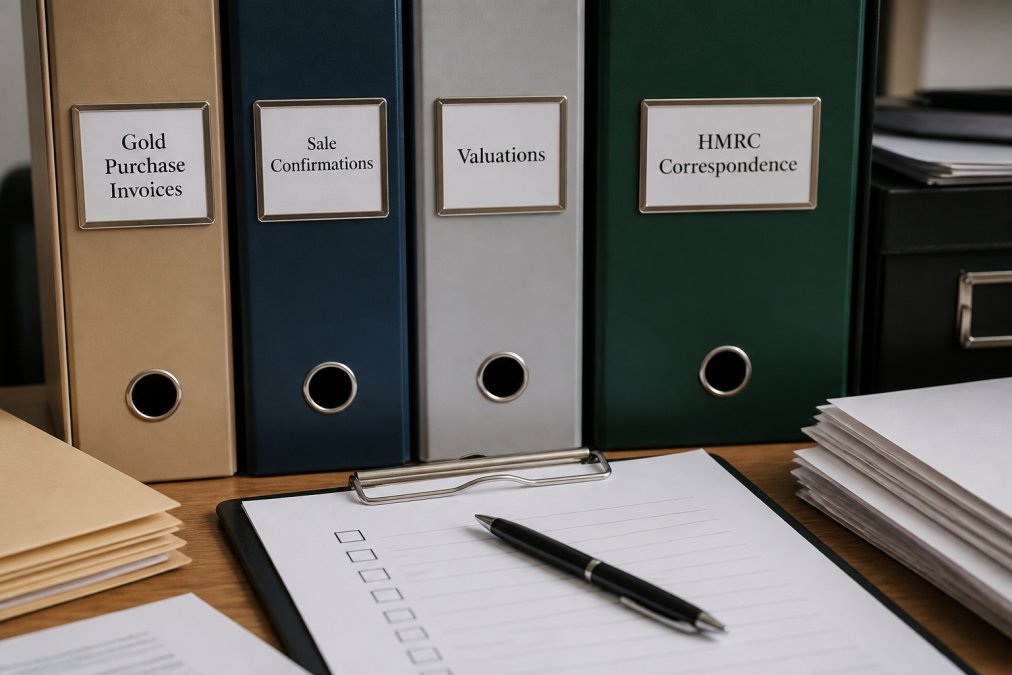
For bullion bars, maintain a file per purchase with dealer name, date, weight, fineness, and cost per gram. Record sales with date, buyer, weight, fineness, and price per gram. For coins, label each purchase clearly noting legal tender status (exempt) or numismatic status (taxable), with dealer description and certificates. For inherited gold, store death certificate, professional valuation, and probate documentation to establish base cost for CGT.
Digital vs. paper records
HMRC accepts both digital and paper records, but they must be legible and complete. If you keep digital copies, ensure they're stored securely and backed up; a lost hard drive is not an acceptable excuse for missing records. Many investors photograph invoices and store them in a cloud folder alongside a spreadsheet tracking purchases and sales. This hybrid approach provides both security and easy retrieval.
For gold held in a SIPP or SSAS, your scheme administrator maintains formal records, but you should still keep personal copies of transaction statements and valuations. If your scheme provider goes out of business or loses records, your personal copies protect you.
Tax implications of gold investment for non-residents
Non-residents face different tax rules depending on residency status, departure date, and gold location. CGT rules can apply in specific circumstances; understanding residency timing is critical to minimising tax exposure.
Determining UK tax residency
Tax residency is determined by the Statutory Residence Test (SRT), which considers days in the UK (fewer than 16 days if non-resident for three prior years means non-resident status), family location, and full-time UK work.
HMRC's guidance on residence and the Statutory Residence Test
If you're leaving the UK permanently or for an extended period, your residency status changes on a specific date.
Split-year treatment and departure dates
Timing your gold sales as a departing resident
Non-residents and CGT exemptions on coins
Double taxation and tax treaties
Reporting requirements for non-residents
Frequently Asked Questions
Do I pay Capital Gains Tax on gold coins in the UK?
Capital Gains Tax applies to most gold bullion bars and coins when you sell them at a profit. However, certain legal tender coins, such as Sovereigns and Britannias, are exempt from CGT. The exemption applies only to coins that are British legal tender and meet fineness requirements. When you sell taxable gold, the gain is the difference between your acquisition cost and selling price. You must report the disposal to HMRC if your total gains exceed your annual exempt amount (£3,000 for the current tax year).
Is gold bullion exempt from VAT?
Investment gold bullion is exempt from VAT when sold in the form of coins or bars meeting specific fineness standards (typically 99.5% purity or higher). This exemption applies to most bullion coins and bars purchased as investments. However, VAT may apply to collectible or numismatic coins valued primarily for rarity rather than metal content, or to jewellery items. Gold2u's 1 Gram Gold Emirates Bar and Tayer Gold Bar both qualify for VAT exemption as investment-grade bullion.
How does Inheritance Tax apply to physical gold?
Physical gold, including coins, bars, and jewellery, forms part of your estate and is subject to Inheritance Tax at 40% above the nil-rate band (currently £325,000). Gold coins that are legal tender may receive favourable treatment in some circumstances, but jewellery and collectible pieces are valued at market value on the date of death. Planning ahead, such as gifting gold during your lifetime or holding it in trust, can reduce the IHT burden on your estate. Antique gold jewellery with provenance documentation may have specialist valuation considerations.
What records do I need to keep for HMRC?
Keep detailed records of every gold purchase and sale: the date, quantity, fineness, acquisition cost, and selling price. Retain receipts, certificates of authenticity, and valuation documents. If you hold gold across multiple years, maintain a running log of your holding period and any disposals. These records support your self-assessment tax return and help you calculate your taxable gain accurately. HMRC may request evidence of these transactions during an enquiry, so retain documentation for at least six years after the end of the relevant tax year.
Ready to buy?
See our current gold sovereigns and collectable gold coins, with fast insured UK delivery.
Shop gold coins →


0 comments