

Table of Contents
- Why Physical Gold Coins Matter for Your Portfolio
- Benefit 1: Direct Ownership and No Counterparty Risk
- Benefit 2: Inflation Hedge and Wealth Preservation
- Benefit 3: CGT Exempt Gold Coins in the UK
- Benefit 4: Liquidity of Physical Gold Coin Investments
- Benefit 5: Tangible Assets and Portfolio Diversification
- Storing Physical Gold at Home vs Vault: Security and Insurance
- Quick Comparison: Gold Coins vs Other Investment Options
- Frequently Asked Questions
Last Updated: September 25, 2026
Why Physical Gold Coins Matter for Your Portfolio
Holding physical gold coins offers tangible control over a portion of your wealth that no digital asset or financial intermediary can claim. Unlike stocks or bonds, which exist as electronic entries in a ledger, physical gold coins sit in your possession, real metal with intrinsic value that exists independent of any institution's solvency or policy decision. This distinction matters more than most investors realise, particularly when economic volatility rises or confidence in fiat currency wavers.
Physical gold coins offer five core benefits that address real portfolio gaps. Below, we'll walk through each benefit and show why many investors allocate a portion of their portfolio to physical bullion and collectible coins.
Benefit 1: Direct Ownership and No Counterparty Risk
When you hold a physical gold coin, you own the asset itself, not a claim on it. This direct ownership eliminates counterparty risk, the risk that a third party (bank, brokerage, fund manager) stands between you and your asset.
Physical gold coins bypass this structure. No institution can freeze your account, restrict your access, or declare insolvency. The metal is yours, period.
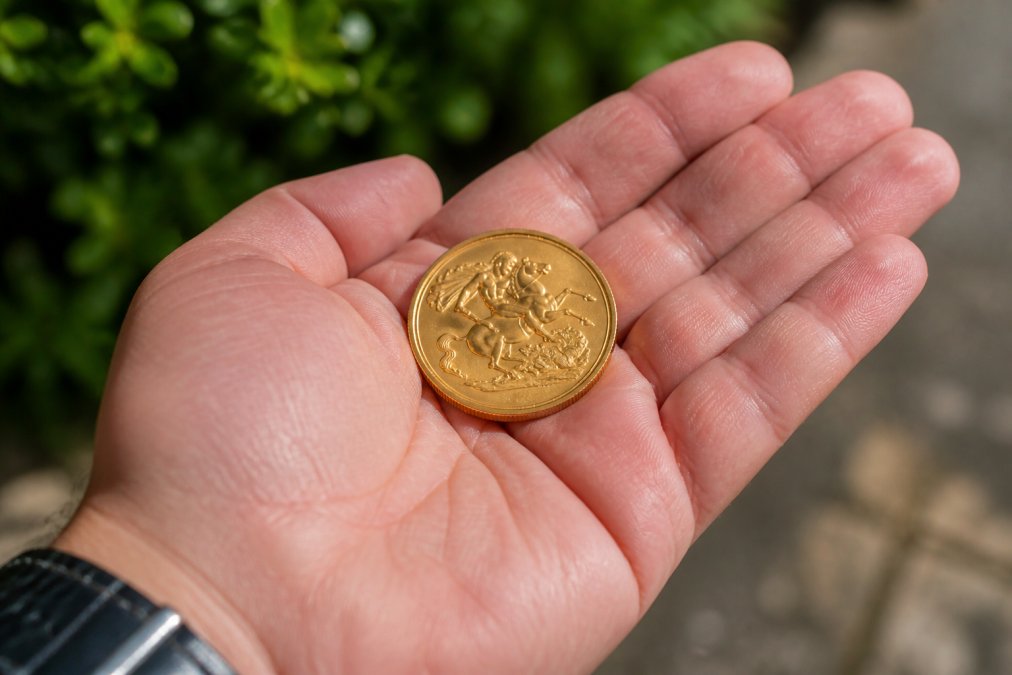
This matters during financial crises. When confidence in the banking system falters, those holding physical assets are insulated from the contagion. Historical precedent supports this: during currency crises or banking collapses, physical precious metals often retained value while digital holdings became inaccessible or were subject to capital controls.
Gold2u specialises in authenticated historical and bullion coins precisely because this direct ownership model appeals to investors seeking genuine diversification away from financial system dependencies. Coins like the 1871 Queen Elizabeth II Full Gold Sovereign at £850 combine intrinsic bullion value with the security of direct ownership.

Benefit 2: Inflation Hedge and Wealth Preservation
Physical gold coins have historically served as an inflation hedge, maintaining purchasing power when fiat currency loses it. This relationship has been consistent enough across decades to make gold a standard portfolio diversifier.
When central banks increase money supply or governments run persistent deficits, cash purchasing power declines. Gold tends to rise in nominal value as the currency weakens, offsetting the erosion.
Unlike stocks (whose value depends on inflation-affected earnings) or bonds (fixed in nominal terms and destroyed by inflation), gold maintains relatively stable real value across economic cycles.
Gold coins also hedge against geopolitical uncertainty, currency devaluation, and loss of confidence in financial institutions. Physical gold coins become portable wealth that transcends borders and institutional dependency.
Benefit 3: CGT Exempt Gold Coins in the UK
A major benefit for UK investors is the capital gains tax exemption on certain physical gold coins. Gold coins that are legal tender and minted after 1837 are exempt from CGT when you sell them for a profit.
This exemption applies to sovereigns and other bullion coins struck by national mints and designated as legal tender (Investment gold coins (VAT Notice 701/21A)). It does not apply to gold bars, gold jewellery, or numismatic coins valued primarily for rarity rather than metal content.
The tax advantage is substantial. If you purchase physical gold coins and sell at a profit, you owe no capital gains tax. This contrasts sharply with shares or gold ETFs, both subject to CGT.
Gold2u's collection includes coins specifically structured for this tax advantage. The 2017 Queen Elizabeth II Full Gold Sovereign at £1,050 is explicitly noted as exempt from capital gains tax, a bullion sovereign struck in 22-carat gold, 0.916 fineness, with 0.2354 troy ounces of fine gold per coin. These are British legal tender and VAT-free, adding to the tax efficiency.

Benefit 4: Liquidity of Physical Gold Coin Investments
Physical gold coins offer strong liquidity for a tangible asset. Unlike real estate or fine art, gold coins have active secondary markets with established buy-back prices and dealer networks.
Bullion coins, sovereigns, and other standardised investment coins are highly liquid. Dealers maintain standing buy-back prices, and you can typically sell within days.
Numismatic coins, rare historical pieces valued for scarcity and condition, are less liquid and may take weeks or months to sell.
For most investors seeking liquidity, bullion coins are the answer. Gold2u offers a range of bullion sovereigns and coins designed for this purpose. The 2002 Queen Elizabeth II Half Gold Sovereign at £420 is a smaller denomination option that provides flexibility: you can sell a portion of your holding if needed without liquidating your entire position.
1871 - Queen Elizabeth II - Full Gold →

The key to maintaining liquidity is holding coins with established secondary markets. Exotic or obscure coins may be beautiful but difficult to sell quickly. Stick to recognised bullion coins or historically significant pieces with established collector demand.
Benefit 5: Tangible Assets and Portfolio Diversification
Tangible assets, physical possessions with intrinsic value, serve a distinct role in portfolio diversification. Unlike financial assets (stocks, bonds, derivatives), which exist as claims or contracts, gold coins are among the most portable tangible assets available.
Diversification reduces portfolio risk by spreading exposure across assets that don't move in lockstep. Stocks and bonds often correlate during market stress. Gold, by contrast, often moves inversely to equity markets, particularly during downturns. Adding physical gold coins reduces overall volatility and smooths returns across market cycles.
The tangibility offers psychological and practical benefits. You can hold the asset, inspect it, and verify its authenticity. Many investors find comfort in knowing a portion of their wealth exists as physical metal they can access immediately.
Portfolio diversification through tangible assets also hedges against systemic financial risk. If equities crash due to credit crisis or bond markets freeze due to interest rate shock, physical gold coins remain unaffected. They're not claims on a company's future earnings or a government's creditworthiness. They're inert metal with historical value across centuries and cultures.
Gold2u's curated collection supports this diversification strategy. Coins ranging from the 2002 Half Gold Sovereign at £420 to the 1917 King George V Full Gold Sovereign from Perth Mint at £1,200 allow investors to build a tangible position scaled to their portfolio size.
Storing Physical Gold at Home vs Vault: Security and Insurance
Once you own physical gold coins, storage becomes a practical concern. You face a choice: keep coins at home or store them in a professional vault. Each option carries distinct security, insurance, and accessibility trade-offs.
Home Storage: Control and Accessibility
Storing gold coins at home gives you direct access and complete control. You can inspect your holdings whenever you wish, and you avoid ongoing storage fees. For smaller quantities, a handful of coins worth a few thousand pounds, home storage is manageable.
The drawbacks are real.
Professional Vault Storage: Security and Cost
Insurance Considerations
The Practical Decision
Quick Comparison: Gold Coins vs Other Investment Options
| Investment Option | Liquidity | Counterparty Risk | Tax Efficiency | Tangibility | Inflation Hedge |
|---|---|---|---|---|---|
| Physical Gold Coins | High (bullion) | None | CGT exempt (UK legal tender coins) | Yes | Strong |
| Gold ETFs | Very High | Yes (fund issuer) | Subject to CGT | No | Strong |
| Gold Bars | High | None | Subject to CGT | Yes | Strong |
| Stocks | Very High | Yes (company, broker) | Subject to CGT | No | Weak |
| Bonds | High | Yes (issuer, broker) | Subject to income tax | No | Weak |
| Real Estate | Low | Yes (lender if mortgaged) | Subject to CGT | Yes | Strong |
| Cash / Savings | Very High | Yes (bank) | Subject to interest tax | Yes | Weak |
Physical gold coins occupy a unique position: they combine the security of tangible ownership with reasonable liquidity, tax efficiency in the UK market, and inflation protection. They're not perfect, storage and insurance add friction, but they address specific portfolio gaps that other assets cannot fill.
Frequently Asked Questions
Are gold coins considered legal tender for capital gains tax purposes in the UK?
Sovereign coins and certain other UK legal tender gold coins are exempt from capital gains tax (CGT) when you sell them. This exemption applies to coins struck by the Royal Mint and other recognised mints, provided they meet specific criteria. This tax advantage makes physical gold coins a particularly attractive investment vehicle compared to gold bars or other precious metals held outside legal tender status.
What is the liquidity of physical gold coin investments compared to other assets?
Physical gold coins offer good liquidity because they're widely recognised and traded. You can sell them to dealers, private buyers, or auction houses relatively quickly, though selling prices depend on current spot prices and numismatic value. Unlike stocks or bonds, there's no centralised exchange, so timing and buyer availability matter. Established coins like sovereigns (£790-£1,200 depending on year) tend to be easier to sell than rare or specialised pieces.
Is it better to store physical gold coins at home or in a vault?
Home storage offers convenience and direct control but carries security risks and requires adequate insurance. Vault storage with a professional provider is more secure but involves ongoing costs and reduced accessibility. Many investors use a hybrid approach: keep smaller quantities at home for liquidity and store larger holdings in vaults. Consider your insurance requirements carefully, as home storage typically requires specialist cover and may have higher premiums than vault-based options.
How much of my portfolio should be allocated to physical gold coins?
Financial advisers typically recommend allocating 5-10% of a diversified portfolio to precious metals, though this varies based on your risk tolerance, investment goals, and economic outlook. Physical gold coins work best as a hedge against inflation and economic uncertainty rather than as a primary investment. Start with smaller purchases (like the 2002 Half Gold Sovereign at £420) to understand the market, then adjust your allocation based on your personal circumstances and broader asset mix.


0 comments