

Table of Contents
- The $1,000 Gold Investment: A 10-Year Performance Breakdown
- Gold vs Stocks: 10-Year Comparison
- Inflation-Adjusted Purchasing Power: What $1,000 in Gold Really Bought
- Physical Gold vs Paper Gold: Which Performed Better?
- Capital Gains Tax on Gold Bullion in the UK
- How to Verify Gold Coin Provenance
- Dollar-Cost Averaging vs Lump Sum: Which Wins for Gold?
- Gold in Crisis vs Bull Markets: How It Performed Over 10 Years
- Frequently Asked Questions
Last Updated: September 25, 2026
The $1,000 Gold Investment: A 10-Year Performance Breakdown
What if I invested $1000 in gold 10 years ago? You would be sitting on a meaningful gain today, though the ride was far from smooth. Gold is a tangible asset that tends to hold its purchasing power over long periods, and the past ten years tested that through a pandemic, a cost-of-living squeeze, and shifting interest rates.
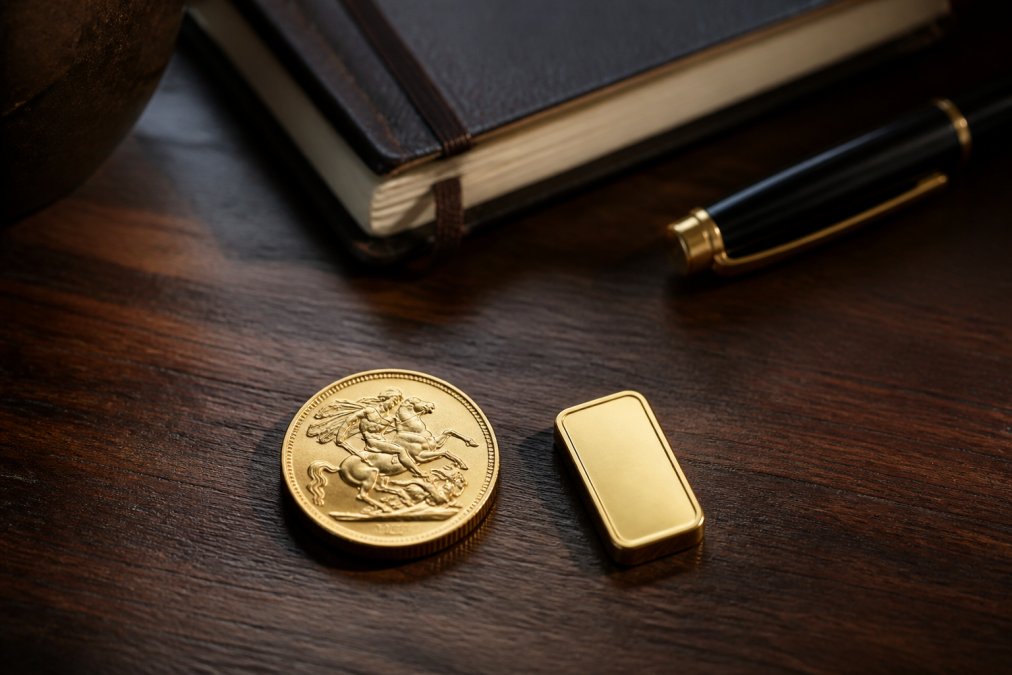
Gold Price in 2016 vs 2026: The Key Numbers
Gold's spot price roughly doubled over the decade, rising from a low base in 2016 to record territory by 2026. Exact figures move daily, so check the London Bullion Market Association price data for the current benchmark rather than relying on a single snapshot.
What $1,000 Would Be Worth Today
What if I invested $1000 in gold 10 years ago? That lump sum would be worth roughly double today in nominal terms, before dealing costs or storage. That is a capital appreciation story, not a yield story: gold pays no dividend and no interest.
| Approach | What you bought | Realistic outcome today |
|---|---|---|
| Lump sum, 2016 | Coins or bars up front | Full decade of price growth |
| Monthly DCA | Small purchases over time | Lower average entry cost, smoother ride |
| Paper gold (ETF) | Fund units | Similar price exposure, annual fees apply |
| Physical bullion | Coins or bars held at home | Price growth plus collectible premium |
Working the Numbers: Entry, Exit and CAGR
Directional talk is easy; the arithmetic is what separates a real answer from a headline. Take a $1,000 lump sum bought at a single 2016 spot price and sold at a single 2026 spot price: if the metal price doubled, gross proceeds are about $2,000, a gain of roughly $1,000.
Now subtract the frictions that a spot-price chart hides:
- Dealer premium on the way in. Physical coins and small bars typically carry a premium over spot, so your $1,000 buys slightly less metal than the spot price implies.
- Dealer spread on the way out. Selling back usually happens below spot, so the exit price is lower than the quoted benchmark.
- Storage and insurance. Home storage is free but carries risk; a vault or safe-deposit arrangement costs money every year.
- Fund fees for paper gold. An ETF or similar product deducts an ongoing charge, which compounds against you over a decade.
The Year-by-Year Shape of the Decade
The decade was not a straight line, which explains why so many investors misjudge gold:
- 2016 to 2018, recovery and drift. Gold climbed off a low base, then marked time as equities ran hard.
- 2019 to 2020, the safe-haven bid. Trade tensions and then the pandemic drove a sharp move higher, with gold making new highs as central banks cut rates and expanded balance sheets.
- 2021, the rate shock. As inflation expectations hardened and policy tightened, gold gave back ground and tested holders' patience.
- 2022, the inflation spike. Consumer prices surged, and gold's role as a store of value came back into focus even as real yields rose.
- 2023 to 2026, the breakout. Renewed demand from central banks and investors pushed the metal into record territory.
What the Same $1,000 Bought in Metal
Dollar figures are abstract; grams are not. If $1,000 bought roughly a third of an ounce of gold at 2016 prices, the same stake buys noticeably less metal today because the price per ounce is higher. That inversion is the point: the metal did not change, the currency did.
Gold vs Stocks: 10-Year Comparison
Stocks beat gold over the decade on total return, largely because reinvested dividends compound while gold does not. A diversified equity index delivered stronger headline growth, but fell harder during the 2020 crash and the 2022 selloff.
Inflation-Adjusted Purchasing Power: What $1,000 in Gold Really Bought
Most guides stop at the nominal number. The more useful question is what that $1,000 in gold actually buys today versus $1,000 in cash, once consumer price inflation is stripped out, the calculation headline comparisons almost never show.
Nominal Return vs Real Return
Nominal return is the change in the pound or dollar value of your holding; real return is that change after subtracting inflation. The two can diverge sharply over a decade, and gold illustrates why.
A simple way to frame it:
- Cash in a current account. If the interest earned is below the rate of inflation, the real value falls every year. The nominal balance may be flat or slightly up while the real balance shrinks.
- Gold. If the metal price rises faster than consumer prices, the real value rises. If it rises more slowly, the real value falls even though the nominal figure is higher.
- The honest answer. Over a full decade, gold has generally preserved purchasing power better than idle cash, but it has not done so smoothly or in every year.
Why the Hedge Is Imperfect
The phrase 'inflation hedge' oversells the relationship. Gold pays no coupon that rises with the cost of living and does not track the consumer price index tick for tick. What it does is hold value against currency debasement over long horizons, a different, narrower claim.
Working Through the Real-Value Calculation
You do not need a spreadsheet to sanity-check the real return. Three steps are enough:
- Find the nominal end value. Take the $1,000 stake and apply the decade's price change to get the gross proceeds.
- Find the cumulative inflation rate. The Office for National Statistics publishes the Consumer Prices Index, and the cumulative change over ten years is the figure to use. Check the ONS consumer price inflation data for the current series rather than relying on a remembered number.
- Deflate the nominal value. Divide the end value by one plus the cumulative inflation rate. The result is what the holding is worth in today's purchasing power.
What the Same Money Bought in Cash
Run the same exercise on cash and the contrast is stark. A sum left in a current account earning little or no interest loses purchasing power every year inflation is positive. Over a decade of even moderate inflation, its real value can fall by a meaningful margin, and the loss is invisible on the statement because the nominal balance never drops.
The Practical Takeaway for a UK Holder
For a UK investor, the inflation-adjusted case for gold rests on three things:
- It is a store of value, not a growth asset. Judge it against cash and inflation, not against a equity index.
- The holding period matters. Over ten years the record is broadly positive; over shorter windows it can be negative in real terms.
- Currency and tax both bite. Sterling moves change the real return, and the CGT treatment of the specific coins you hold changes what you keep.
Physical Gold vs Paper Gold: Which Performed Better?
Physical bullion and gold ETFs track the same underlying price, so raw performance is close. The gap opens up in fees, spreads, and what you actually own.
Capital Gains Tax on Gold Bullion in the UK
Capital gains tax on gold bullion depends on which coins you hold. UK gold Sovereigns and Britannias are legal tender and exempt from capital gains tax, while other bullion coins and bars are not.
How to Verify Gold Coin Provenance
Verifying gold coin provenance means confirming where a coin was minted, when, and that it is genuine. This matters most for historical pieces, where a fake or cleaned coin can cost you dearly.
A practical checklist before you buy:
- Check the mintmark to confirm the minting location
- Match the design and portrait to the correct year
- Weigh and measure the coin against its official specification
- Ask for any certification or grading documentation
- Buy from a seller who shows the actual coin you will receive
Dollar-Cost Averaging vs Lump Sum: Which Wins for Gold?
Dollar-cost averaging beats lump-sum investing for most gold buyers, not because it produces a higher return, but because it removes the stress of timing the market. Gold is volatile, and buying at a single peak can take years to recover.
Gold in Crisis vs Bull Markets: How It Performed Over 10 Years
Gold shines in crises and lags in strong bull markets. Over the past decade, its best stretches came during periods of fear: the 2020 pandemic shock and the 2022 inflation spike, when equities wobbled and investors sought a safe-haven asset.
Frequently Asked Questions
Has gold been a good investment over the last 10 years?
Gold delivered a positive total return over the past decade, though with notable ups and downs. A $1,000 investment in 2016 would have grown to roughly $2,000 by 2026, depending on the form of gold and purchase premiums. That return beat inflation but lagged a strong US stock market. Gold's value lies in its low correlation to equities and its role as a safe-haven asset, making it a useful diversifier rather than a pure growth play.
How do I calculate the historical return on gold investments?
Use the formula: (Current price - Purchase price) / Purchase price x 100. For a $1,000 investment, if gold rose from $1,200 to $2,400 per ounce, the return is 100%. Adjust for any dealing fees, storage costs and the buy-sell spread. For a more accurate picture, use the annualized return: ((End value / Start value) ^ (1 / number of years)) - 1. This gives the compound annual growth rate (CAGR), which smooths out yearly volatility.
Is it better to invest in physical gold or gold ETFs?
It depends on your goals. Physical gold, such as bullion coins and bars, gives you direct ownership with no counterparty risk, but incurs storage and insurance costs and a wider buy-sell spread. Gold ETFs offer liquidity and low expense ratios, but you rely on a custodian and cannot take delivery. For long-term wealth preservation and tangible asset allocation, physical gold, especially CGT-exempt coins like the [2017 Gold Sovereign](https://gold2u.co.uk/products/1871-queen-elizabeth-ii-full-gold-sovereign-copy) at £1,050.00, can be a preferred choice. For short-term trading, ETFs are more convenient.
What are the tax implications of selling gold in the UK?
In the UK, bullion coins that are legal tender, such as the Gold Sovereign and Britannia, are exempt from Capital Gains Tax (CGT). Other forms of gold, including bars and non-legal-tender coins, may be subject to CGT if your total gains exceed the annual exempt amount. Gold is also VAT-free. Always keep purchase records. For personalised advice, consult a tax professional.
Ten years of gold data points to one conclusion: the metal rewards patience, not clever timing. If you want to add physical gold to your portfolio, Gold2u offers authenticated historical coins, natural gold nuggets, and antique jewellery, each with verified provenance and transparent pricing. Browse the collection and start building a position you can hold for the next decade.


0 comments