

Table of Contents
- Why Gold Acts as a Hedge During Market Turbulence
- Gold and Stock Market Correlation: What the Data Shows
- How Much Gold to Hold in a Portfolio
- Physical Gold vs Gold ETFs: Which Hedge Suits You
- Gold Investment Risks You Need to Understand
- Building Your Gold Hedge: A Step-by-Step Allocation Plan
- Frequently Asked Questions
Last Updated: October 21, 2026
Why Gold Acts as a Hedge During Market Turbulence
Using gold to hedge against market volatility works because its price tends to move independently of shares, so losses in one are often offset by gains in the other. It is a physical asset with no company behind it, no dividend to cut and no balance sheet to fail.
That independence is the whole point. When stock markets fall, investors often move money into gold as a safe haven. Demand rises, and the price usually holds up or climbs while equities slide.
We have watched this pattern repeat across several market shocks. It does not work every single time, and gold can fall too. But as portfolio protection against market risk, it has a long record.
This guide from Gold2u explains how to use gold as a hedge against market volatility, how much to hold, and which format suits your goals.
Gold and Stock Market Correlation: What the Data Shows
Gold's correlation with the stock market is usually low and often negative during sharp sell-offs. In plain terms, the two assets rarely move in lockstep, which is exactly what a diversifier should do. But the headline correlation figure hides as much as it reveals, because the relationship changes with the type of market stress.
A useful way to read the evidence is to split market history into regimes and ask how gold behaved in each. The pattern most practitioners describe looks like this:
- Equity sell-offs driven by fear: gold has often risen or held firm as investors move into safe-haven assets. This is the regime where the hedge earns its keep.
- Inflation shocks: gold has historically tended to keep pace with or outrun consumer prices over long periods, though the relationship is loose year to year and can lag when real yields rise sharply.
- Recessions: gold has often held up better than cyclical equities, but it is not immune, in liquidity crunches investors have sold gold to raise cash, so it can fall alongside shares for short stretches.
- Rising-rate periods: this is the weakest regime for gold. When real yields climb, the opportunity cost of holding a non-yielding asset rises, and gold has frequently struggled.
- Currency stress: for a pound-based investor, gold's return is partly a currency story. Sterling weakness can lift the gold price in pounds even when the metal is flat in other currencies, and sterling strength can do the reverse.
According to the World Gold Council's research on gold as a strategic asset, gold has historically delivered positive returns in most years while showing low correlation to equities. The important caveat is that correlation is not constant: it tends to fall when equities fall hardest, which is precisely when a hedge matters most, but it can drift higher in calm or rising-rate markets.
Rather than rely on a single correlation number, measure the hedge on the outcomes you actually care about:
- Correlation: the direction and strength of co-movement with your equity holdings, ideally measured over rolling periods rather than one long window.
- Drawdown reduction: how much smaller your portfolio's worst peak-to-trough fall was with gold than without it.
- Volatility: whether adding gold lowered the overall swing in portfolio value.
- Downside capture: how much of the equity market's losses your portfolio absorbed in falling months.
A common pattern is that a modest gold holding improves drawdown and downside capture more than it changes average returns. That is the practical case for the metal, not that it always rises, but that it often moves differently when it matters. Judge gold on its long-term performance and its behaviour in a crisis, not on short-term price movements.
How Much Gold to Hold in a Portfolio
A common starting allocation is 5% to 10% of a portfolio in gold. Many investors treat that range as enough to matter without letting one asset dominate their risk. The harder question is not the number itself but how you set it, how you keep it, and how you adapt it to your own circumstances.
Set the allocation from the risk you are trying to offset. Work backwards from the outcome you want. If your goal is to soften a bad year rather than rescue it, the lower end of the range is usually enough. If you hold a concentrated equity portfolio or a long time horizon, a slightly higher weight can make sense because you can tolerate more gold volatility in exchange for more crisis protection. If you already hold commodities, mining shares or other real assets, count them towards the same bucket so you do not double up on the same risk.
Choose a rebalancing rule before you buy. A target weight only works if you maintain it. Two simple rules cover most investors:
- Calendar rebalancing: review once a year on a fixed date and top up or trim back to target. This is simple, low-cost and easy to stick to.
- Threshold rebalancing: act when gold drifts a set distance from target, commonly a few percentage points either way, which avoids unnecessary trades in quiet markets.
Either rule forces you to sell gold after it has run up and buy it after it has fallen, which is the discipline that turns a holding into a hedge.
Adapt to risk tolerance, not to headlines. Nervous investors often prefer the upper end of the range because the psychological comfort of a larger hedge helps them stay invested elsewhere. Investors with a high equity weighting and a steady income may prefer the lower end and accept a smaller cushion. There is no single correct number, but there is a correct process: write the target down, state the rebalancing rule, and review it against your circumstances rather than against the latest market move.
Work through a simple example. Suppose a portfolio is worth £100,000 and you set a 7% target, or £7,000 in gold. If gold rallies and the holding grows to £9,000 while the rest of the portfolio is flat, threshold rebalancing would trim roughly £2,000 back into your other assets. If gold falls to £5,000, the same rule would top it up. Over time this mechanical discipline is what keeps the hedge at the size you chose.
A 5% holding will soften a bad year but not rescue it. A 10% holding gives real portfolio protection but adds more gold volatility of its own. We suggest starting near the lower end, building up as you learn how the metal behaves, and letting your rebalancing rule do the work. Asset allocation is personal, and the process matters more than the precise percentage.
4.638g Natural Gold Nuggets – The Investor’s Lot – Premium Australian Specimen →
Physical Gold vs Gold ETFs: Which Hedge Suits You
Physical gold gives you direct ownership of a tangible asset with no counterparty risk. A gold ETF gives you exposure through a fund, with easy buying and selling but a paper claim rather than metal in hand.

Here is how the main routes compare:
| Option | What You Own | Best For | Watch Out For |
|---|---|---|---|
| Physical gold | The metal itself | Long-term holders and collectors | Storage, insurance, wider spreads |
| Gold ETFs | Fund shares | Quick, low-effort exposure | Annual fees, no physical metal |
| Mining shares | Company equity | Higher growth potential | Company and market risk |
| Futures | A contract | Short-term trading | Use, expiry, complexity |
Physical gold suits investors who want a core asset they can hold for years. ETFs suit those who want exposure without storage. Mining shares and futures are trading tools, not simple hedges.
For collectors, natural gold nuggets add a second layer of value. Our 4.638g Natural Gold Nuggets - The Investor's Lot is a good example: a curated set of Australian nuggets at £1,229.07 that carries both gold weight and collectable appeal.
Gold Investment Risks You Need to Understand
Gold is not a guaranteed shield. It can fall sharply, and it can stay flat for years. Anyone using gold to hedge against market volatility needs to accept that the hedge itself carries risk.
The main gold investment risks are:
- Price swings: gold volatility can be high in the short term
- No income: gold pays no interest or dividend
- Currency effects: pound-based returns shift with exchange rates
- Storage and insurance: physical holdings cost money to keep safe
- Timing risk: buying at a peak can mean a long wait to recover
Gold works best as part of a wider risk management plan, not as a single fix.
Building Your Gold Hedge: A Step-by-Step Allocation Plan
Start with a target allocation, choose your format, then buy in stages. The goal is a steady position you can hold through market turbulence, not a quick trade.
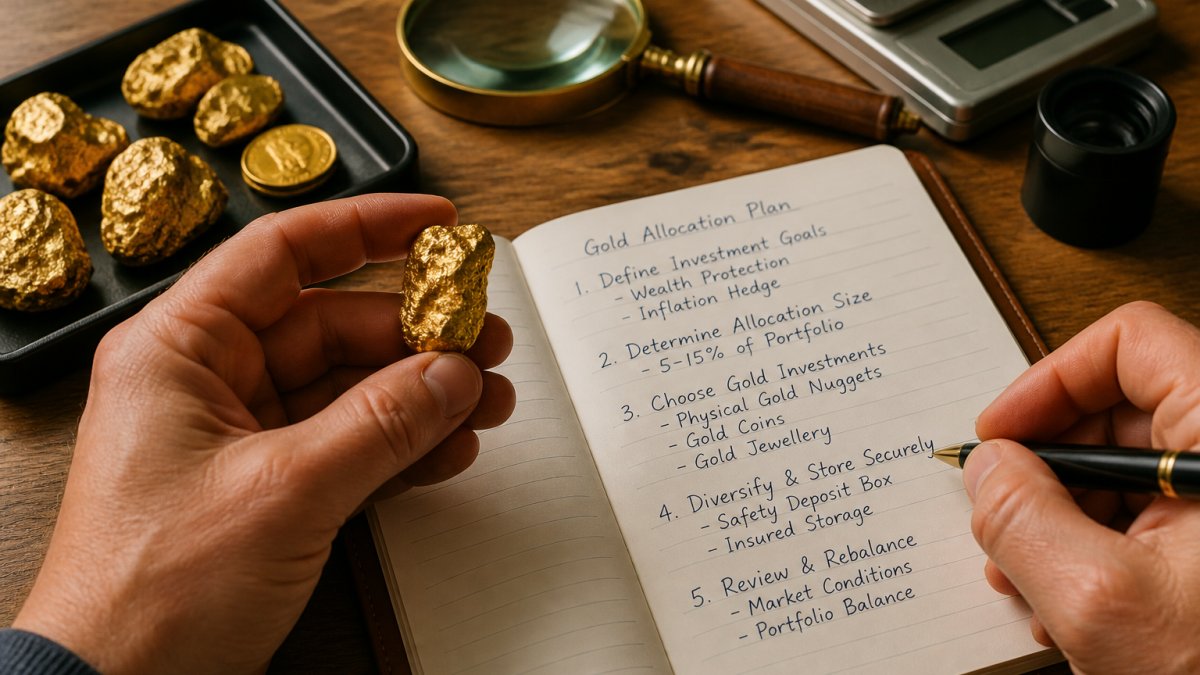
Here is how we would do it:
- Set your target. Decide on a percentage, often 5% to 10%, and write it down.
- Pick your format. Physical gold for long-term holding, an ETF for simplicity.
- Split your buying. Spread purchases over several months to smooth price movements.
- Store it safely. Use a secure vault or insured home storage for physical metal.
- Review yearly. Rebalance if gold grows past your target weight.
- Measure the hedge. Compare gold's performance against your equities in down markets.
A simple checklist to keep you on track:

- Target allocation written down
- Format chosen and costs understood
- Buying schedule set
- Storage and insurance arranged
- Annual review date booked
For collectors who want tangible gold with character, our 8.055g Natural Gold Nugget - The Boss at £2,899.57 offers a substantial natural specimen, while the 5.311g Natural Gold Nuggets - The Trader's Lot at £1,407.41 sits neatly in the mid-range. Each piece is unaltered Australian gold, so you hold real metal with its own natural character.

Frequently Asked Questions
Is gold inversely correlated with stocks?
Not perfectly, and not all the time. Gold and stock market correlation shifts with the regime: during sharp equity sell-offs gold often moves independently or rises as investors seek a safe haven, but in calm markets the correlation can drift positive. That is why gold works best as a diversifier held alongside equities rather than a guaranteed mirror-image hedge. Review the correlation over several years rather than a single quarter before deciding how much weight to give it.
How much gold should you hold in a diversified portfolio?
Many investors hold between 5% and 10% of a portfolio in gold, with 10% to 15% for those who want stronger protection against market volatility. The right figure depends on your time horizon, existing equity exposure and tolerance for gold's own price swings. Start at the lower end, measure how the position behaves through a market drawdown, then adjust. Rebalance annually so a rising gold price does not quietly push your allocation beyond the level you intended.
Is physical gold a better hedge than gold funds?
It depends on what you need from the hedge. Physical gold, such as natural nuggets or coins, gives you direct ownership with no counterparty and no ongoing fund fee, but it carries storage, insurance and resale costs. Gold ETFs are cheaper to trade and easy to sell in small amounts, yet you rely on the provider and pay annual charges. For long-term protection, many investors split between the two, holding physical gold for permanence and a fund for liquidity.
What are the risks of using gold to hedge against market volatility?
Gold can fall when you need it most, and its short-term volatility is real: prices swung sharply in 2008 and again in 2025, rising around 43.9% and 52.9% in pounds in those years respectively. Storage and insurance add cost, and selling physical pieces can take time. Currency matters too, since gold is priced in dollars and pound moves affect your return. Size the position so a 20% gold drawdown would not derail your wider plan.
Market turbulence will come again, and a portfolio with no hedge feels every dip. Gold2u helps investors add tangible gold through natural Australian nuggets and historical coins, each with authenticity you can trace. Explore our curated nugget collections and build a physical gold position that balances your portfolio against market risk. Get started with Gold2u and hold gold you can actually see.


0 comments